· ReadyStack
Worked example
Real numbers from this tool, line by line.
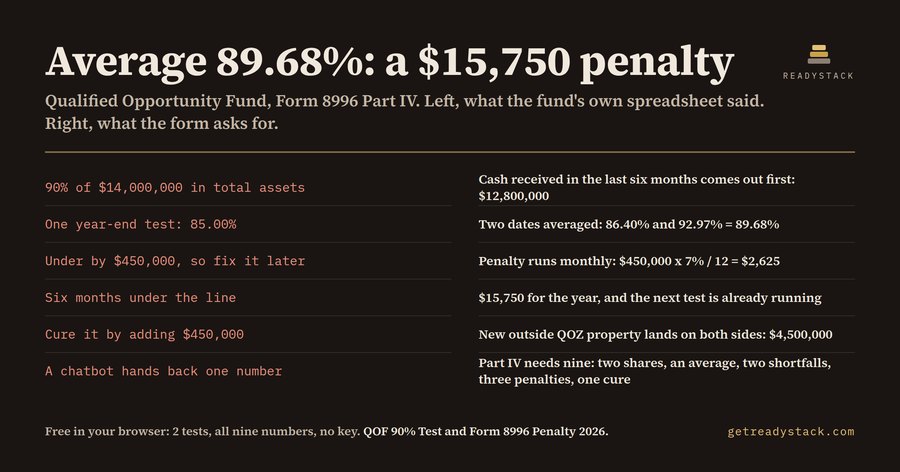
A $450,000 shortfall on a single testing date cost one calendar-year Qualified Opportunity Fund $15,750 in section 1400Z-2(f)(1) penalty for 2026, and the fund manager's own spreadsheet said the test had been passed. The spreadsheet was not wrong about the arithmetic. It was wrong about which arithmetic Form 8996 asks for.
Here is the fund, exactly as it was typed into the extension. On the first testing date, June 30, total assets were $12,500,000 and qualified opportunity zone property was $10,800,000, with no cash contributed in the prior six months. On the second testing date, December 31, total assets were $14,000,000 and QOZ property was $11,900,000, with $1,200,000 of cash received inside the six months before that date under a written working-capital plan. The fund was under 90% for six months of the first half and none of the second. The IRS underpayment rate entered was 7%, the rate the IRS carried through the fourth quarter of 2026.
Three things fall out of that.
The first is the denominator. Cash a fund receives in the six months before a testing date, held under a written working-capital plan, is left out of total assets for that date. So December 31 is not 90% of $14,000,000. It is measured against $12,800,000, and the QOZ share on that date is 92.97%, not 85.00%. Turn that carve-out off in the tool and the same fund's second date drops to 85.00% and its shortfall jumps from zero to $700,000.
The second is that there are two dates, not one. Form 8996 tests the last day of the first six-month period of the tax year and the last day of the tax year, then averages the two percentages. This fund's dates are 86.40% and 92.97%, so the average is 89.68%. Under the line by a third of a percentage point, on a year where one of the two dates was comfortably clear.
The third is the shape of the penalty. It is not a flat fine. Section 1400Z-2(f)(1) charges the shortfall times the section 6621 underpayment rate divided by twelve, for each month the fund is below 90%. At $450,000 and 7%, that is $2,625 for every month it stands. Six months is $15,750, and the clock does not stop because the tax year ended.
That leads to the number most people get wrong by a factor of ten. Asked how much it takes to cure a $450,000 shortfall, almost every answer is $450,000. But new QOZ property lands on both sides of the ratio: it raises the qualified assets and the total assets together. Solving for the contribution that puts the fund back on 90% gives $4,500,000, not $450,000. Converting assets already on the balance sheet is the $450,000 route. Bringing in outside money is the $4,500,000 route. The tool prints both, side by side, so the conversation with the investment committee starts from the right one.
The extension runs all of it in the tab where the trial balance already is. Ten inputs, nine answers: the share on each testing date, the Form 8996 average, the shortfall on each date, the penalty for the first-half months and the second-half months, the penalty for the year, and the cure. No key, no cap, no watermark, every number free.
The $60 licence is on a different axis. It does not unlock an answer. It keeps the work: the month-by-month penalty schedule exported to .csv for the workpaper file, and an alarm before each testing date, so the next test is measured on the day rather than reconstructed from memory in March.
The yardstick is the penalty itself. At the 7% rate the IRS held through the fourth quarter of 2026, a $450,000 shortfall costs $2,625 for every month nobody notices it.
15 seconds — what it actually does
Full walk-through
Questions people ask
What does this extension actually work out?
It runs the Form 8996 90 percent asset test on both testing dates a calendar-year fund has, June 30 and December 31, averages them the way the form does, and prices the section 1400Z-2(f)(1) penalty month by month at the IRS underpayment rate you enter. It also gives the dollars needed to get back over 90 percent.
Who is it for?
Managers of US Qualified Opportunity Funds and the CPAs who sign their Form 8996. It fits the person holding a trial balance on June 29 who needs to know, before the testing date closes, whether the fund is over the line and what one month under it costs.
Why not just ask a chatbot or use a free online calculator?
Most of them apply 90 percent to total assets and stop. They miss that cash received in the six months before a testing date, held under a written working-capital plan, comes out of the denominator, and they report the cure as the shortfall when new outside money must cover ten times that amount.
What is free and what needs the key?
Every number is free with no key and no usage cap: both percentages, the average, both shortfalls, the monthly penalty and the cure figure. The $60 key adds two things on a different axis, keeping the work: a month-by-month penalty schedule exported to .csv, and an alarm before each testing date.
What would this cost handled another way?
The penalty is its own yardstick. At the 7 percent underpayment rate the IRS carried through the fourth quarter of 2026, a $450,000 shortfall costs $2,625 for every month it stands, and a full six months of it is $15,750. The key is $60 once,.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.